1. 8% cumulative preferred return to investors, accruing only on capital actually called, from the date called; distributions thereafter split 70% Brickstone / 30% investors. The fund receives 30% of the GP economics (capital interest, fees, promote) only on transactions it helps capitalize with its own dollars; it holds no ownership in Brickstone Partners, its other assets or its other fee income, and Brickstone may transact without the fund when fund capital is unavailable. 2. Net LP IRR after the 8% preference on called capital and the 70/30 split, modeled at Brickstone’s standard 2.0x deal execution: 18.2% ($1B capitalized) · 21.4% ($2B) · 23.2% ($3B), ~2.0x MOIC (see Program Scenarios). Cash-on-cash: 5.5% year-one yield on the $2.8M founder-share seed (30% of Brickstone’s 2027 fees and distributions), rising as fund-backed deals begin harvesting in year 6 — annual receipts exceed peak net capital outstanding from that point. Illustrative only; see Disclosures. 3. Offering basis values the founder-share seed at a 5.50% cap rate on AY 26-27 budgeted NOI, at actual 8/1/26 debt balances, with the fund holding a 30% ownership interest in the Brickstone sidecar entity that holds its 50% / 25% / 30% positions (~$2.3M of consideration to Brickstone) plus 30% of Brickstone’s seed-asset fees valued at 10x — a typical GP-stakes multiple for contractual fee-related earnings, cross-checked by DCF. See Valuation and Disclosures. 4. Portfolio average annual returns, 2009–2025, calendar-year basis; actual project-level cash flows through June 30, 2026; prepared August 6, 2026; sponsor records, unaudited. Past performance is not indicative of future results.
No offer or solicitation. This memorandum is furnished on a confidential basis for discussion purposes only. It does not constitute an offer to sell, or a solicitation of an offer to buy, any security. Any offering will be made only to qualified investors pursuant to definitive offering documents, a subscription agreement and the operating agreement of the issuing vehicle, which together will supersede this memorandum in every respect.
Forward-looking statements. This memorandum contains projections, targeted returns and other forward-looking statements based on Brickstone's current assumptions. They are inherently uncertain, are not guarantees of future results, and actual outcomes may differ materially. Past performance — including the track record of Brickstone-sponsored partnerships referenced herein — is not indicative of future results.
Valuation methodology & conflicts of interest. The seed assets are owned by partnerships that Brickstone sponsors and in which Brickstone holds existing capital interests. Brickstone established the seed valuation itself; no independent appraisal has been obtained. The offering basis applies a 5.50% capitalization rate to each asset's AY 26-27 budgeted net operating income (per the firm's August 2026 budget and cash forecast) and a 10x multiple to the conveyed fee share. Capitalization rates materially affect value; investors should form their own view of value. Brickstone will serve as managing member of the vehicle and will receive 70% of distributions above the preferred return — arrangements that create conflicts of interest which will be described in the definitive documents.
Nature of the interest. Interests in the vehicle are not an equity or ownership interest in Brickstone Partners, LLC or any Brickstone affiliate, and carry no claim on Brickstone’s other assets, fee income or promotes. The vehicle participates in GP economics solely on transactions it helps capitalize with its own capital. Fund capital is finite; Brickstone is under no obligation to offer every transaction to the vehicle and may sponsor transactions without it when fund capital is unavailable or unsuitable.
Conveyed interests. The conveyed capital interest is a 30% ownership interest in a Brickstone sidecar entity that holds Brickstone’s own positions in the underlying partnerships (Brickstone Investments, LLC — 50% of 1101 Boulder, LLC; Brickstone Investments IV, LLC — 25% of 2885 Boulder, LLC; Brickstone Investments III, LLC — 30% of 910 Boulder, LLC). Final conveyed percentages, entities and mechanics are subject to definitive documentation, lender consent where required, and the partnerships' governing agreements.
Illiquidity; no market. Interests in the vehicle will be illiquid, will not be registered under the Securities Act of 1933 or any state securities laws, and no public or secondary market will exist. Investors must be prepared to bear the risk of loss of their entire investment and to hold indefinitely. Distributions depend on the performance of the underlying assets and fee streams and are not guaranteed; the preferred return is a priority of distribution, not a promise of payment.
Tax. Nothing herein is tax, legal or accounting advice. Investors will receive Schedule K-1s and should consult their own advisors regarding the consequences of an investment, which will depend on each investor's particular circumstances.
Confidentiality. This memorandum is intended solely for the named recipient, may not be reproduced or redistributed in whole or in part, and must be returned or destroyed upon request. Acceptance of this document constitutes agreement to these terms.
Since 2001, Brickstone Partners has directly completed more than $1 billion of investment and development, with the principal’s own cash committed in every transaction. The general partner’s economics — capital interests, asset-management fees and promotes — have never been shared. This offering shares them for the first time: on every transaction the fund helps capitalize, investors receive 30% of the GP’s capital interest, fees and promote — up to $30 million, with a $20 million follow-on round exercisable anytime during the fund life, a $250,000 minimum investment, an 8% cumulative preferred return on called capital, 70/30 thereafter. Capital is called progressively — annually, as deal flow is deployed — never held idle against the preference. This is a share of deal-level GP economics, not an ownership stake in Brickstone Partners: the fund participates only where its capital is used, and Brickstone may transact without the fund when fund capital is unavailable.
Seeded at closing — not a blind pool. The first $10 million — founder shares — receives a 30% ownership interest in the Brickstone sidecar entity that holds its positions in three stabilized Boulder partnerships — The Mansion (50% Brickstone-held), East Village Flats (25%) and The Gaslamp (30%) — plus 30% of Brickstone’s asset-management fees on those assets: a $2.8M package (~$2.3M of consideration to Brickstone), yielding 5.5% in cash from the first quarter.
The upside is the platform — and the timing. Brickstone sees a rare convergence: a macroeconomic reset and the stress the higher-rate environment has put on commercial real estate are surfacing distressed sellers, reset bases and a closed construction pipeline all at once. Windows like this have arrived roughly once a decade, and Brickstone expects this one to run two to five years. The GP fund is built for it — giving Brickstone the capacity to move faster and grow more aggressively while the opportunity lasts. Remaining fund capacity funds the vehicle's share of the GP position in that deal flow — Boulder recapitalizations and Southeastern value-add multifamily. At Brickstone's standard 2.0x execution, $1–3 billion of new projects capitalized over ten years pays the vehicle $53–140M on $13.3–34.3M contributed — a modeled net LP outcome of ~18–23% IRR at ~2.0x.
Three cash-flowing assets and a contracted fee stream at closing — valued at a 5.50% cap on budgeted NOI.
Contractual acquisition and management fees pay the vehicle every year — $0.80M per $100M capitalized — regardless of exit timing.
Investors earn the full 8% on called capital before Brickstone takes a dollar above its retained 70%.
Each fund-backed transaction adds ~$3.3M of profit per $100M capitalized — capital interest, fees and promote together.
| Structure | Closed-end investment in a newly formed Brickstone GP co-investment vehicle — not an ownership interest in Brickstone Partners |
| Offering | Up to $30,000,000 of membership interests |
| Minimum investment | $250,000 — the manager may accept smaller commitments at its discretion |
| Founder shares — first $10,000,000 | Receive a 30% ownership interest in the Brickstone sidecar entity holding its positions in 910 Boulder, 2885 Boulder & 1101 Boulder, LLC, plus 30% of Brickstone’s fees on those three assets (~$2.3M consideration to Brickstone) |
| Follow-on round | Up to $20,000,000 additional, exercisable at Brickstone’s election anytime during the fund life |
| Preferred return | 8% cumulative, compounding — accrues only on called capital, from the date called |
| Distribution split thereafter | 70% Brickstone / 30% investors |
| Economics conveyed | On each deal the fund helps capitalize: 30% of GP capital-interest cash flow, 30% of asset-management fees, 30% of promotes |
| Scope | Deal-by-deal — the fund participates only where its capital is deployed; Brickstone may transact without the fund when fund capital is unavailable |
| Seed portfolio | 30% of the Brickstone sidecar entity holding its 50% / 25% / 30% interests in The Mansion, East Village Flats & The Gaslamp — $2.27M + 30% of their fee stream (founder shares) |
| Seed fee strip | 30% of Brickstone’s seed-asset fees to founder shares — $51.5K/yr per the 2027 budget, valued at 10x fee-related earnings (DCF-checked) = $0.51M |
| Seed package basis | $2.8M — 5.50% cap on AY 26-27 budget NOI, 30% fee strip at 10x |
| Capital calls | Seed funded at closing; thereafter called progressively, annually, as deal flow is deployed |
| Distributions | Quarterly, from asset distributions and fee income, beginning first full quarter |
| Future deployments | Remaining capacity funds the GP co-invest on new Brickstone transactions — up to 100% of it, allocated by Brickstone deal by deal — earning the same 30% economics on those deals |
| Reporting | Quarterly investor letters · annual audited financials · annual K-1s |
| Management | Brickstone Partners, managing member — Daniel H. Otis, Principal |
| Targeted closing | Fall 2026 |
Brickstone is a commercial real estate private-equity firm founded in 2001 and headquartered in Franklin, Tennessee. The firm has directly completed more than $1 billion of investment and development — anchored in CU Boulder student housing, extended through multifamily, a Google build-to-suit (site assembled by Brickstone, vertical co-sponsored) and land — with a sophisticated focus on tax-adjusted returns, utilizing unique methods for creating non-cash tax losses. Sponsor cash in Brickstone deals frequently exceeds 10% of the equity — skin in the game institutional sponsors rarely match.
| Founded | 2001 — 25 years |
| Direct investment & development completed | $1BB+ |
| Distributed from The Lodge alone since 2015 | $51.7M |
| Sponsor cash in deals | Frequently >10% |
| Boulder student housing owned | $500MM+ |
| The Lodge — initial 2015 partnership | 53.8% IRR · 3.8x |
| Parker off Pearl — 11-year hold | 26.6% IRR · 4.4x |
| The Mansion — held since 2011 | 100% leased, 3 straight years |
| Full-cycle recapitalizations executed | Two at The Lodge (2019 · 2022) |
| Stream | Basis | Fund Share (fund-backed deals) |
|---|---|---|
| Capital interests | GP cash invested in each partnership — frequently >10% of equity | 30% |
| Asset-management fees | Contractual on the seed assets ($172K in 2027 — fund receives 30%) · 30 bps on total asset value on new deals | 30% |
| Promotes | Typically 20–30% of profits over an 8% investor preference | 30% |

| Investment | Type | Avg. C/C | IRR | Multiple |
|---|
Brickstone Partners historic performance and projected yields. Unaudited and sponsor-prepared. Past performance is not indicative of future results. Detailed historical performance by investment is available on request.
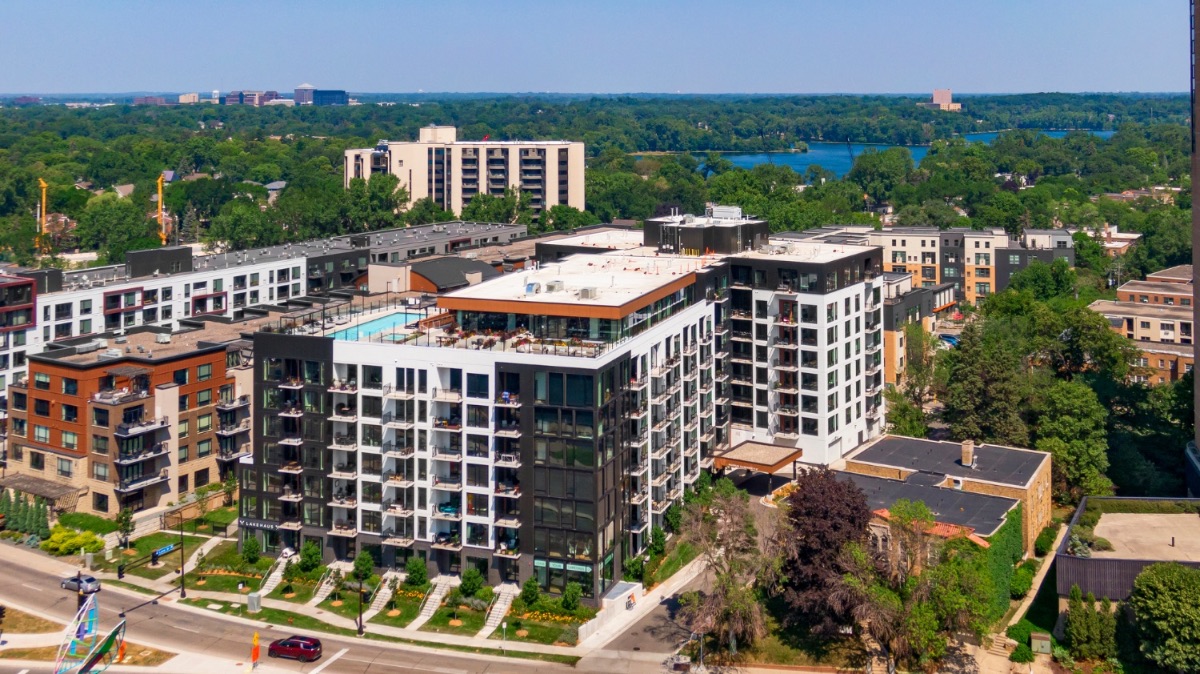
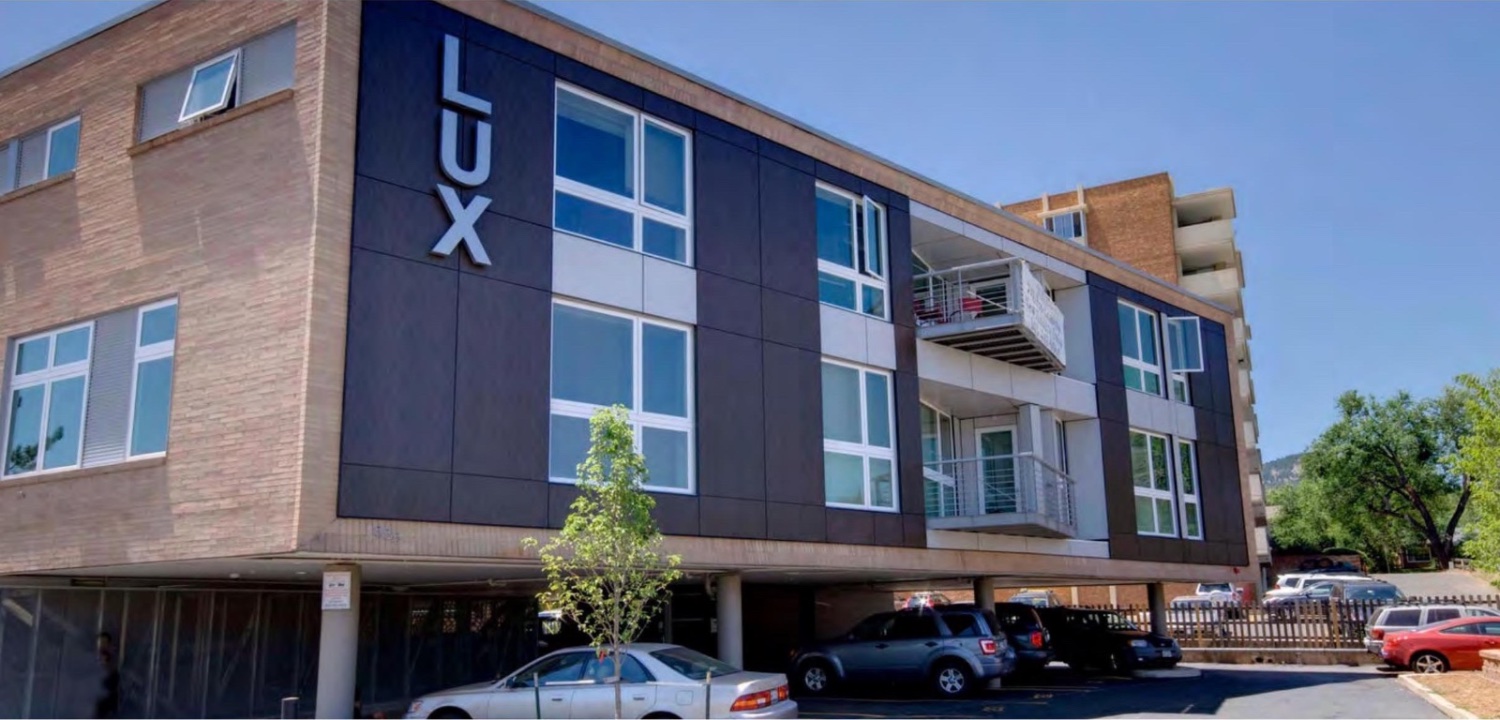
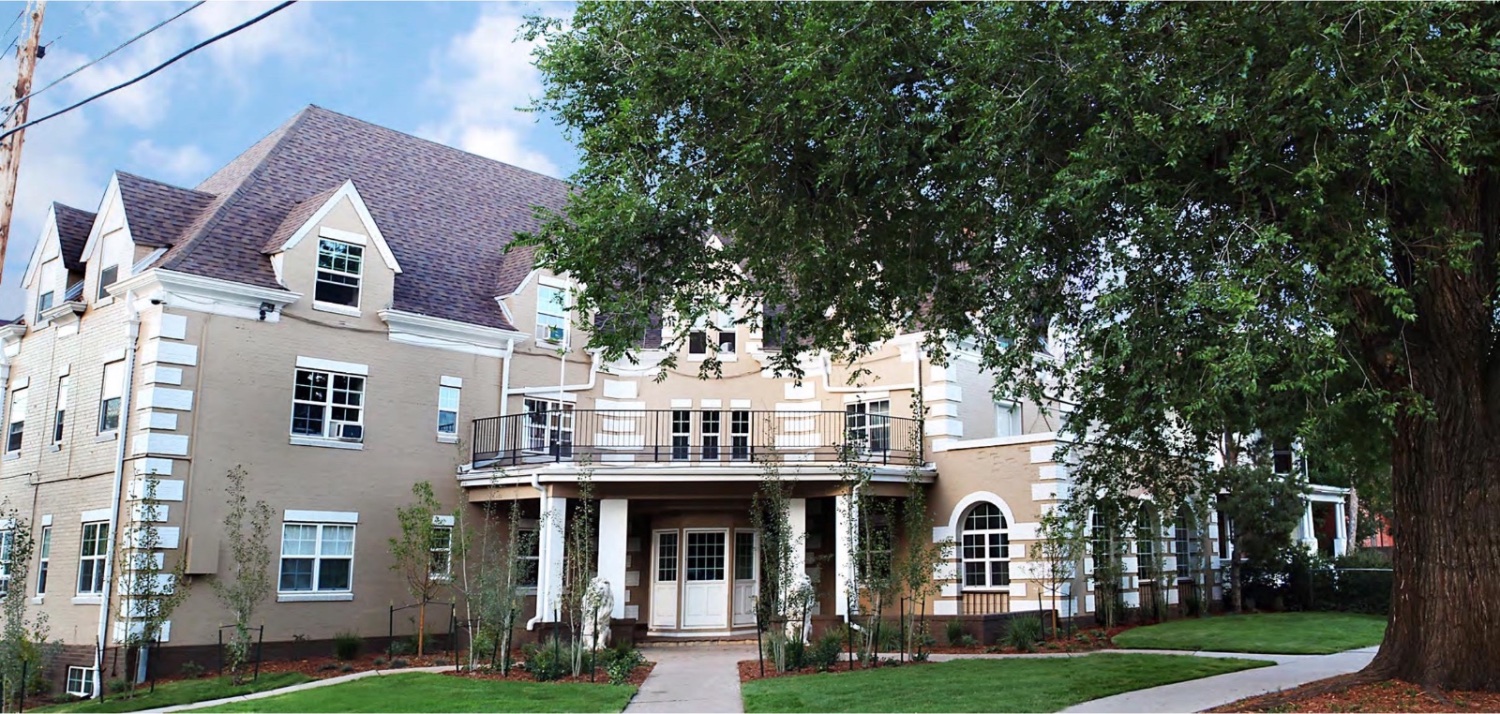
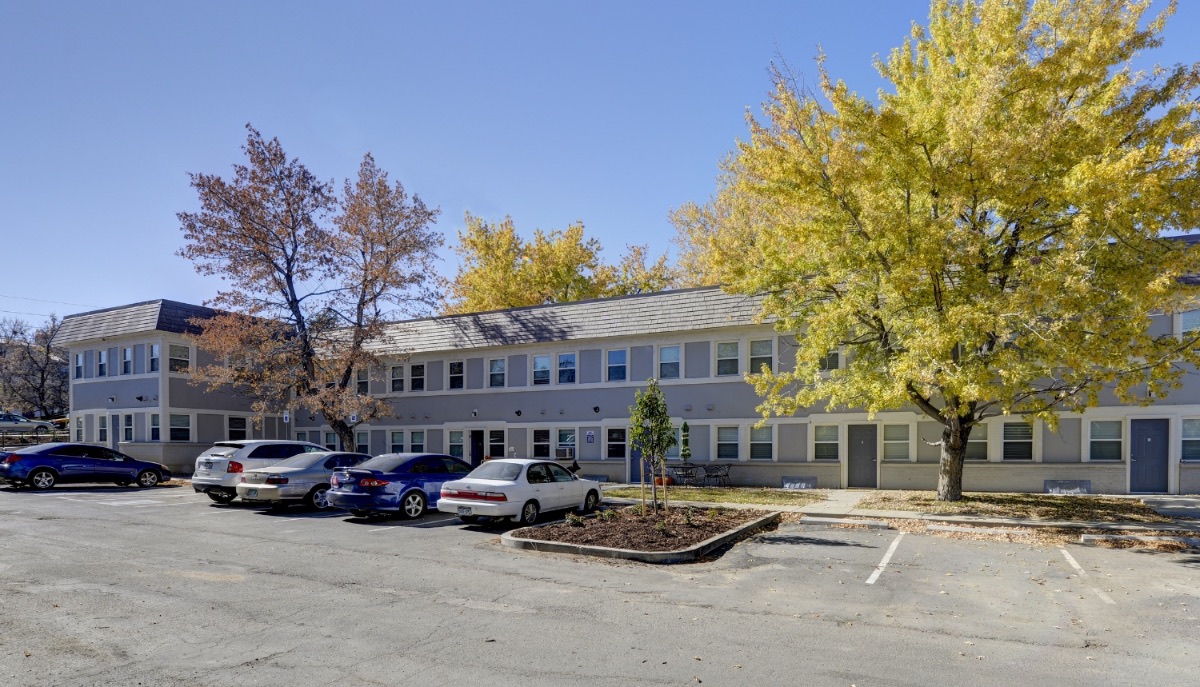
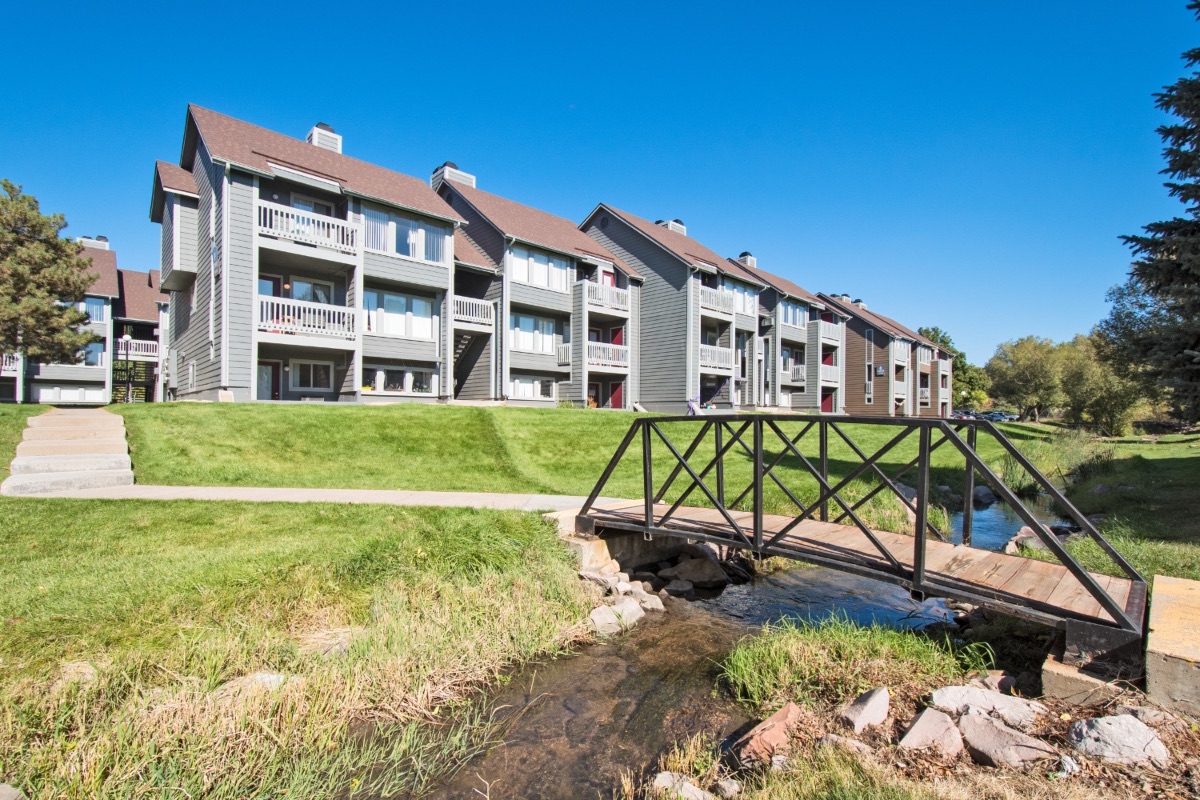
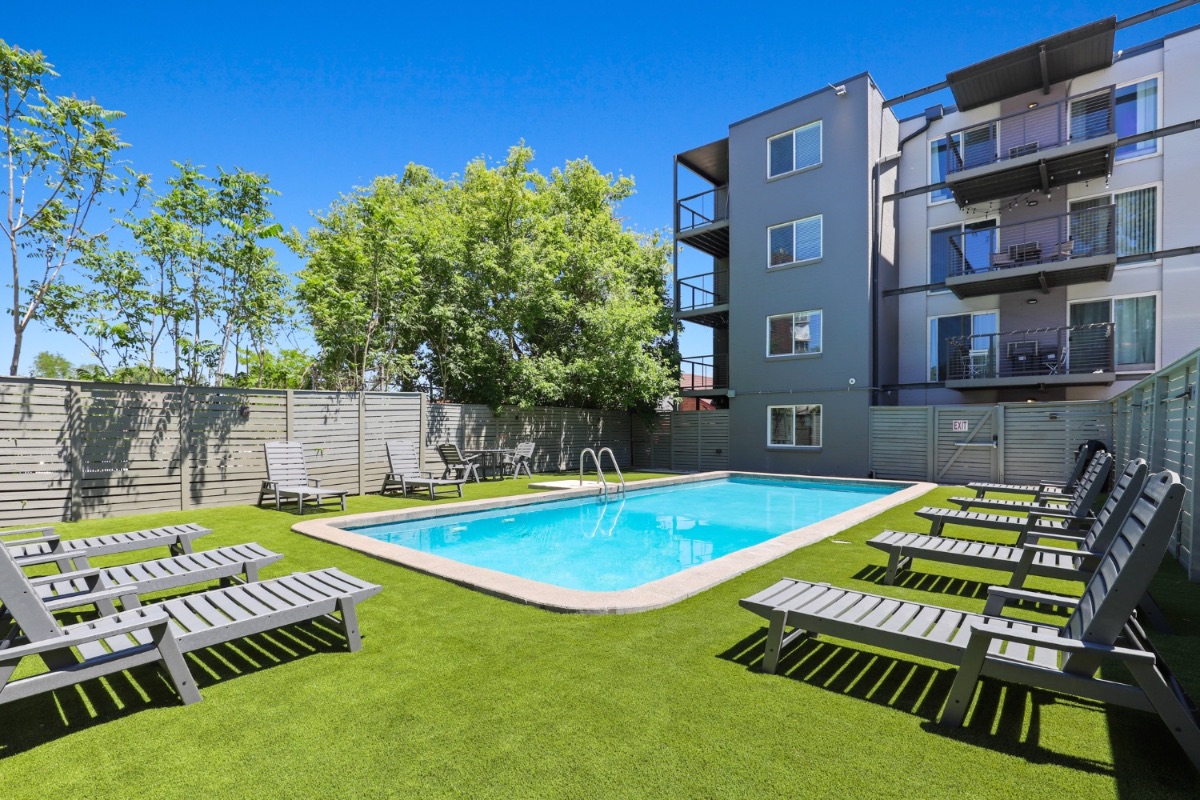
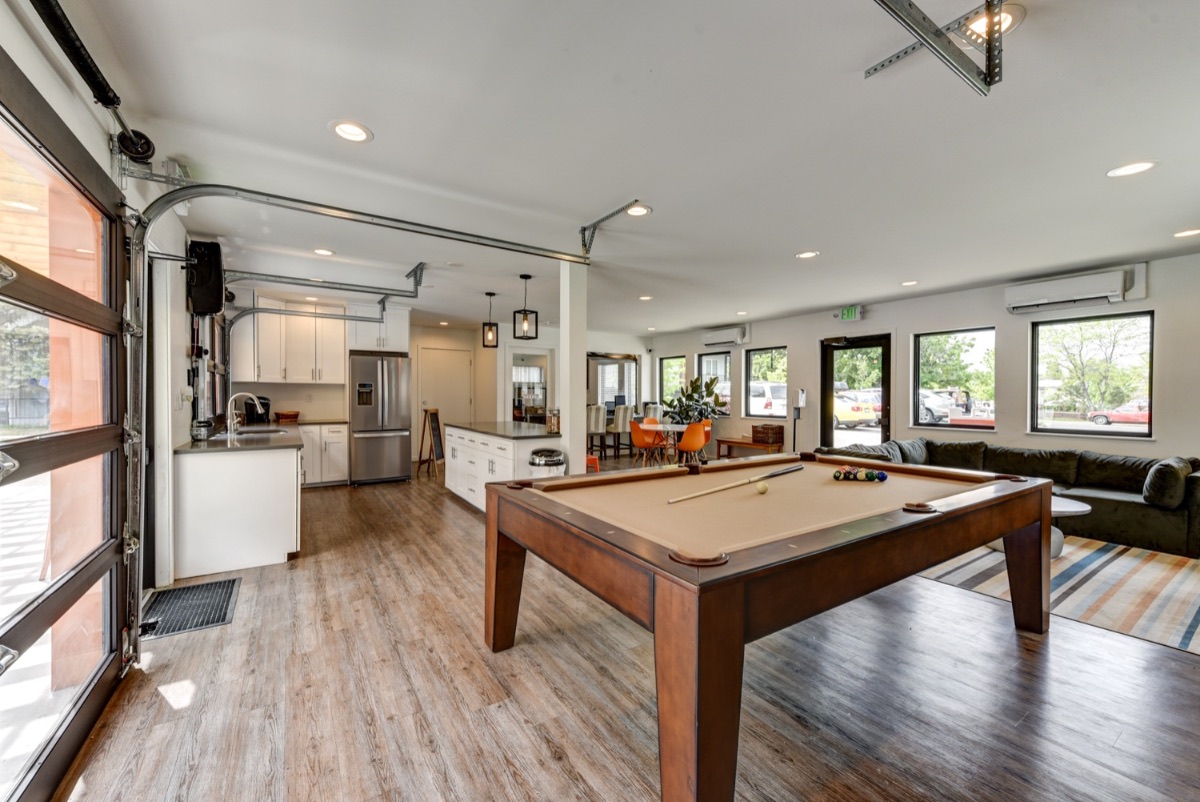
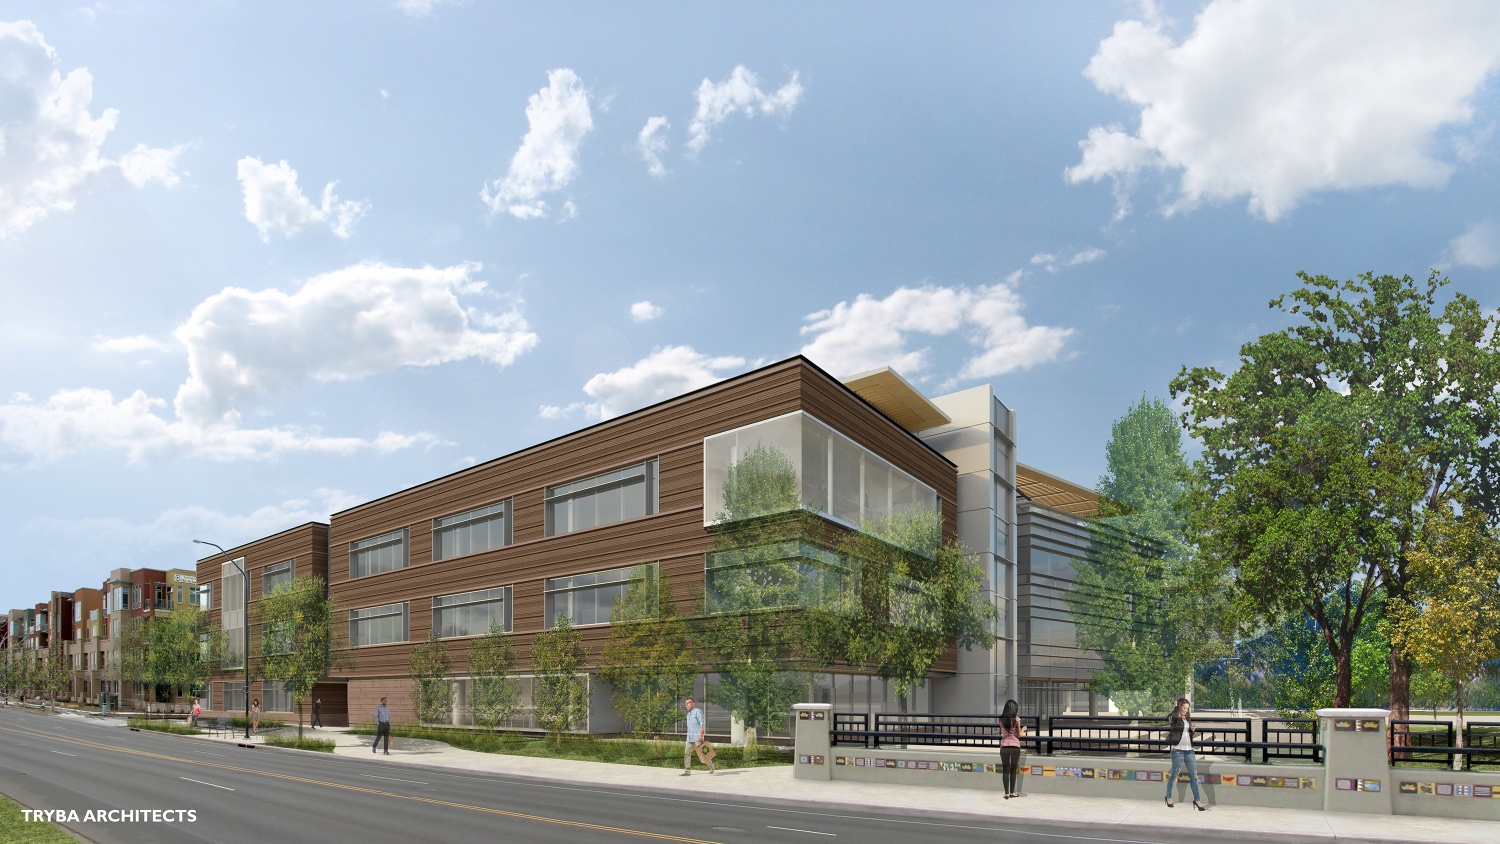
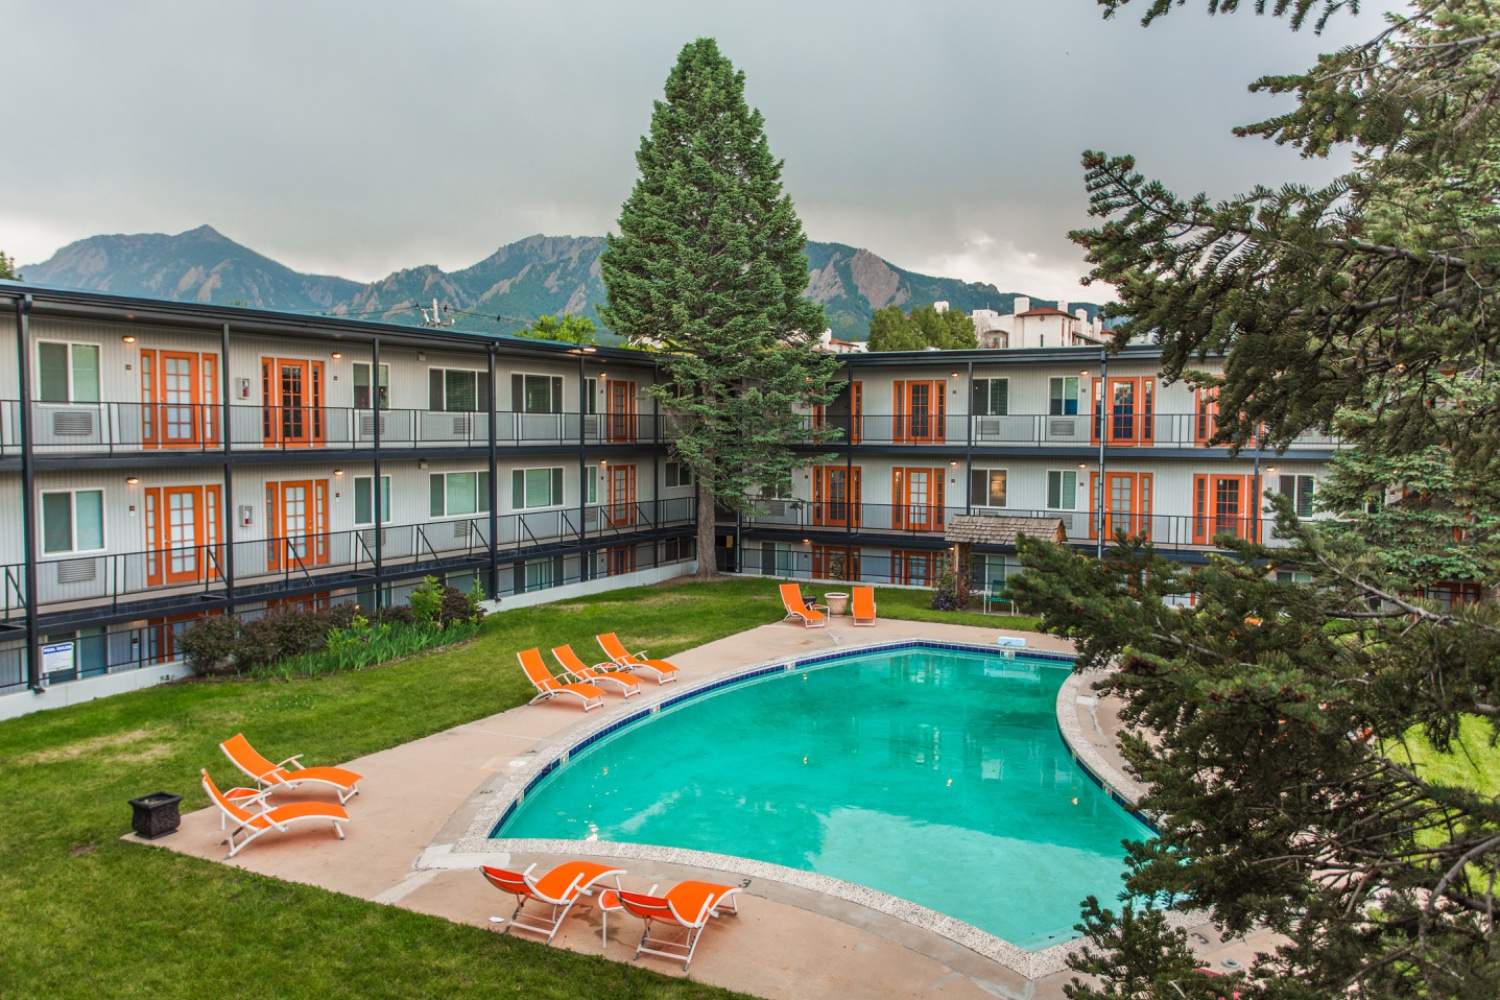
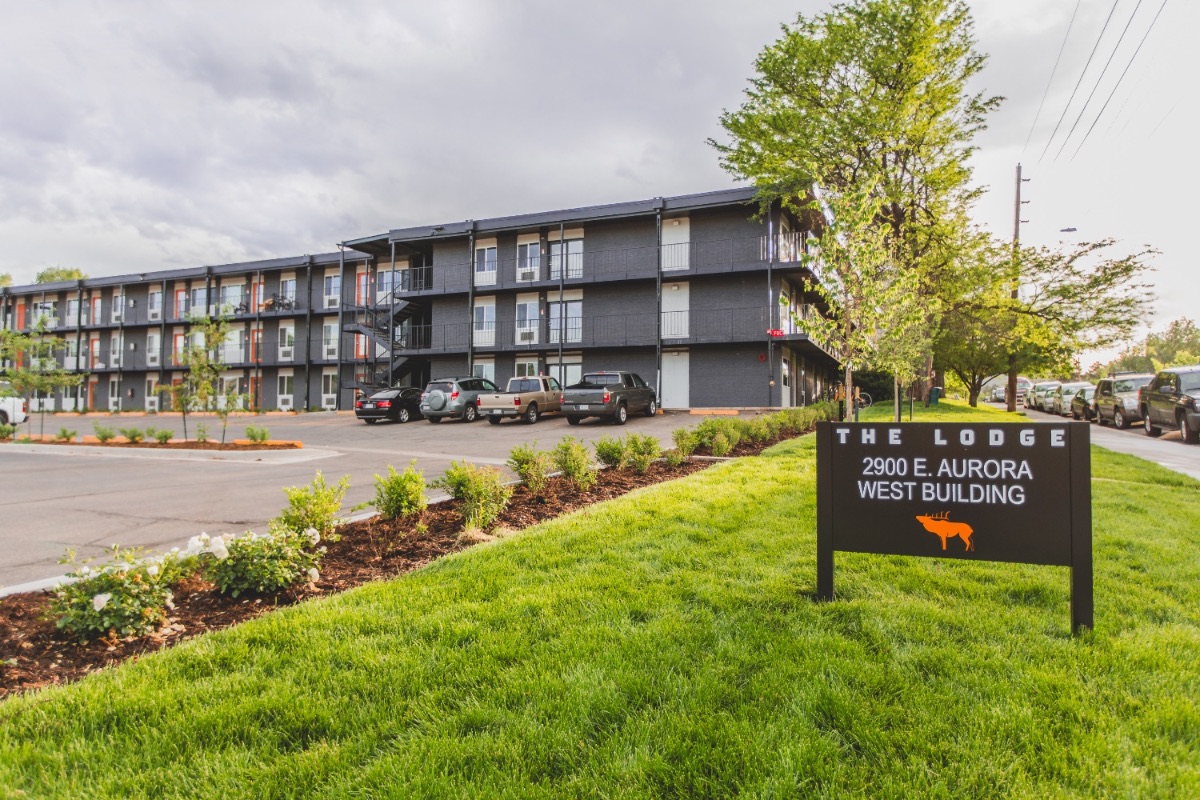
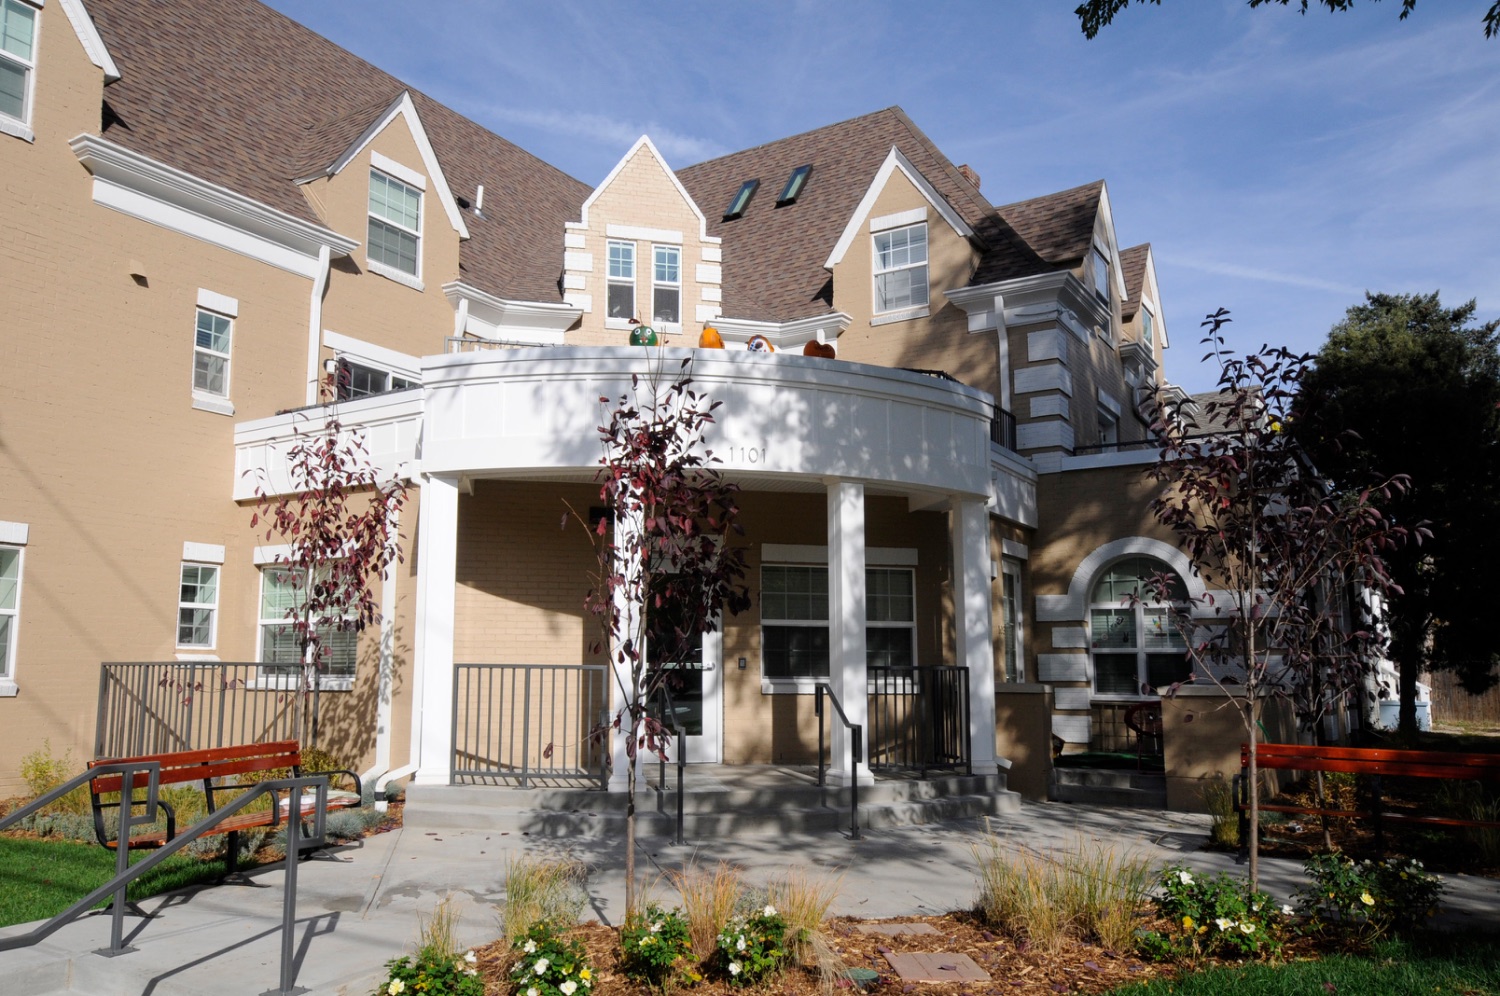
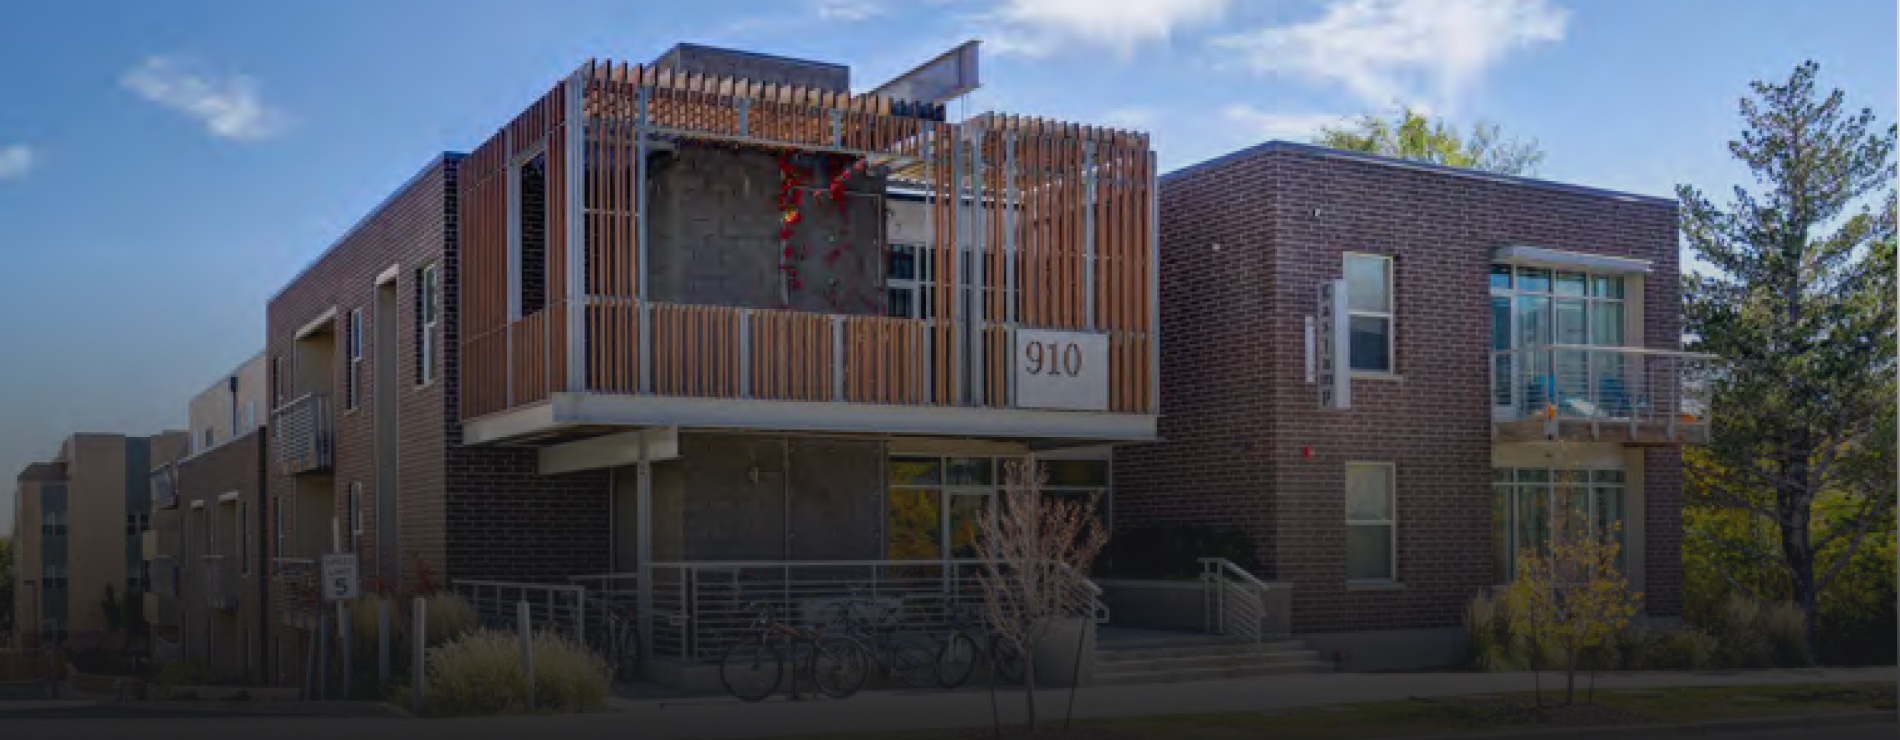
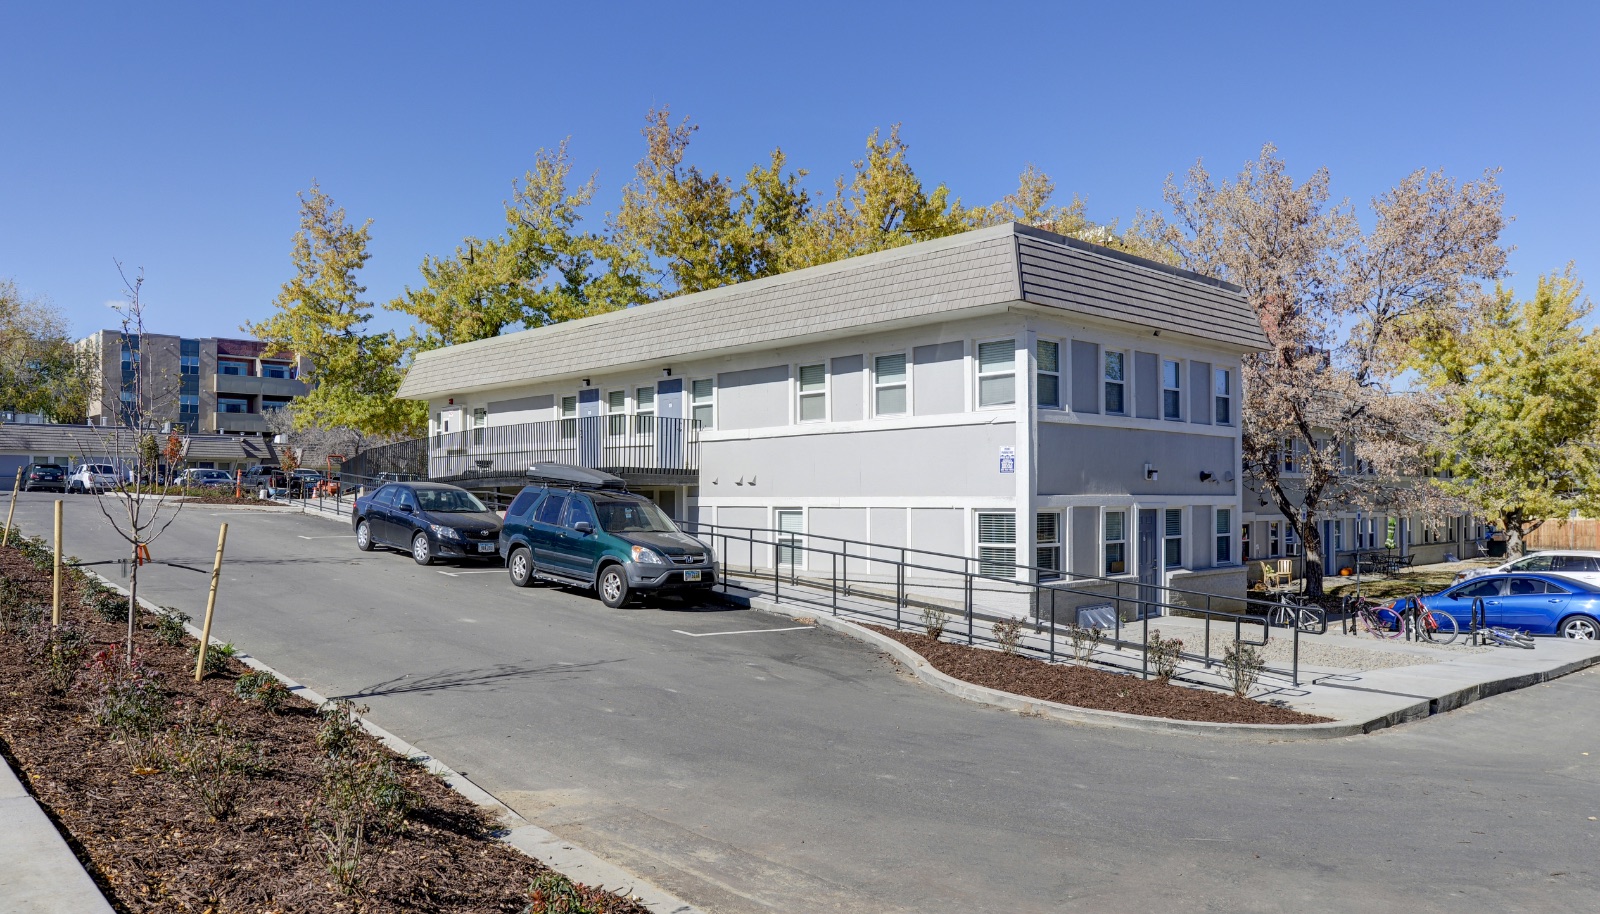
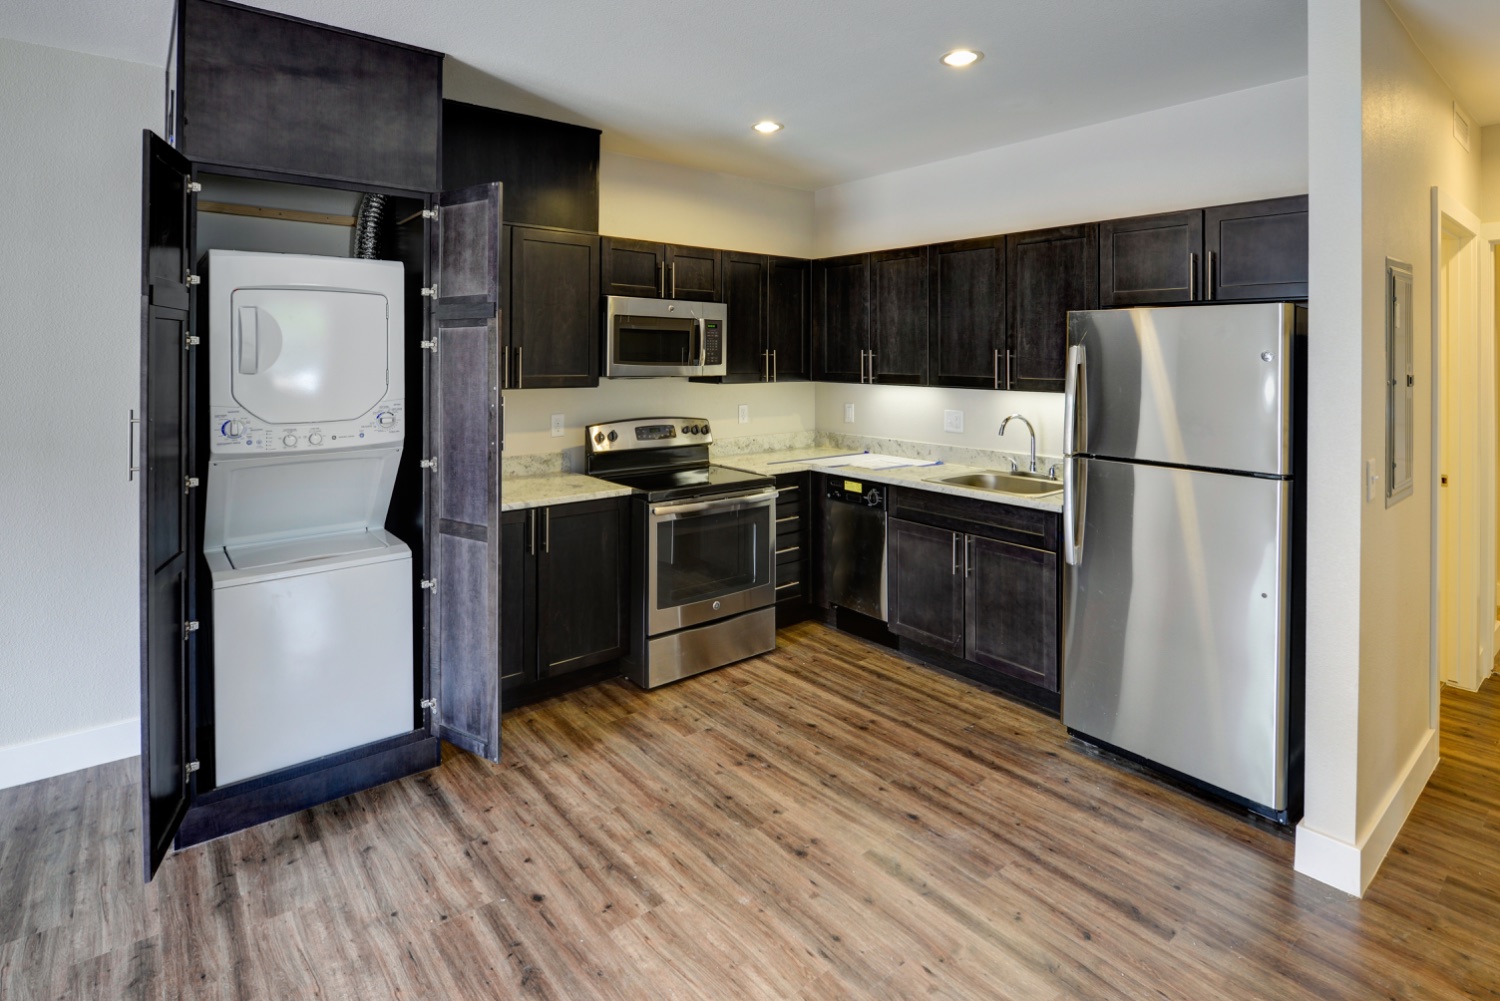
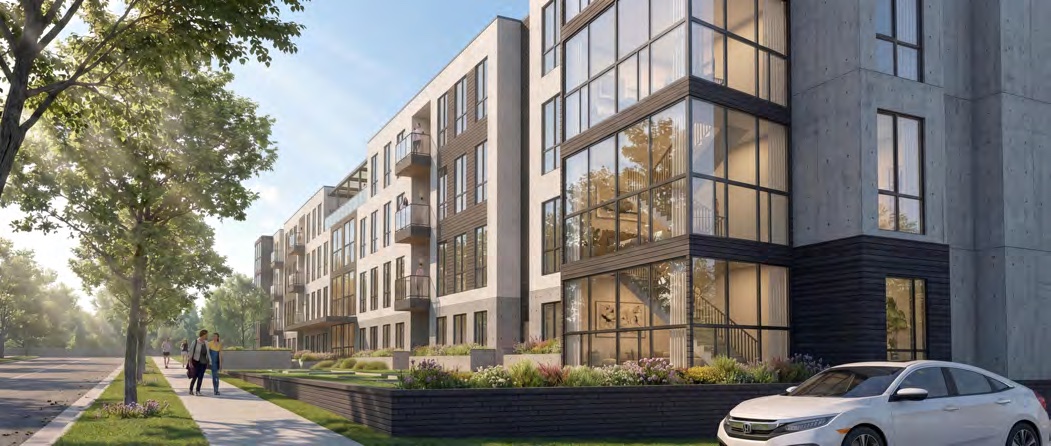
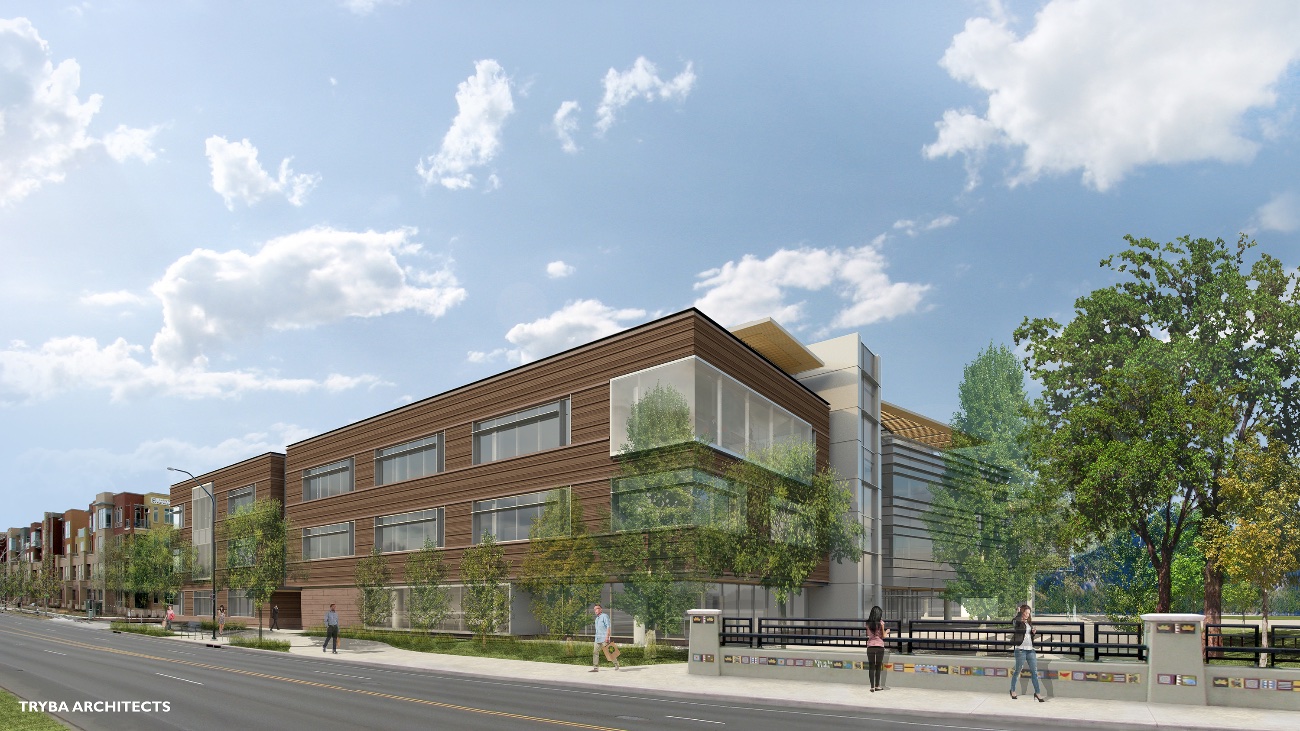
A selection of Brickstone's development and value-add work across Boulder and the Front Range — ground-up development, build-to-suit, and student- and multifamily repositioning.


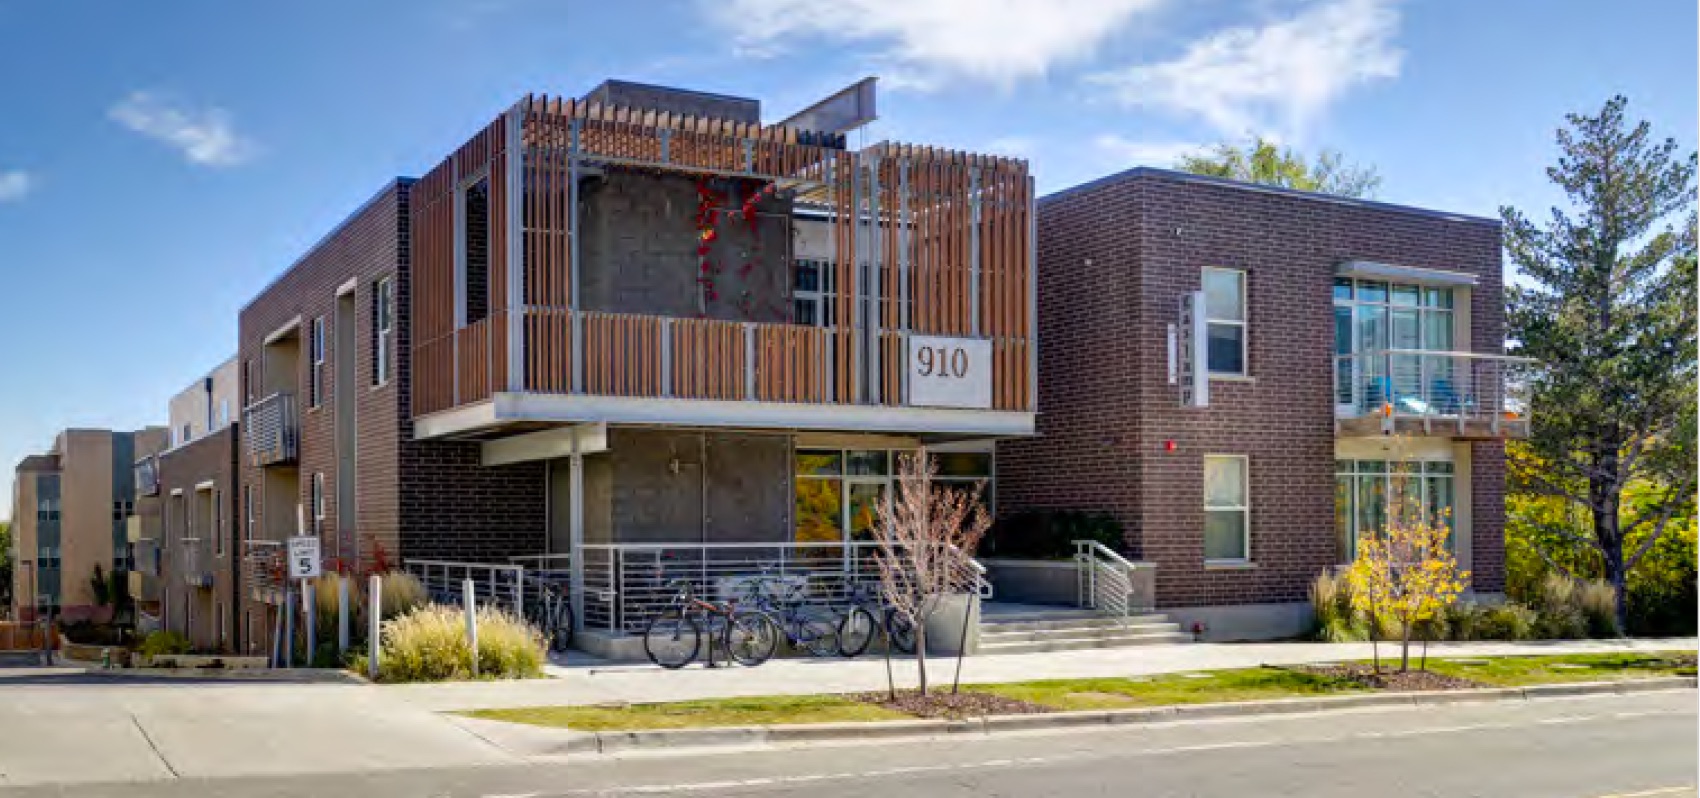
The seed portfolio is three stabilized student-housing partnerships within walking distance of CU Boulder — two developed by Brickstone ground-up (The Gaslamp, 2012; East Village Flats, 2014) and one historic repositioning held since 2011 (The Mansion). All three are Cardinal-managed, conservatively levered at fixed rates, and have distributed cash every year through the hardest student-housing market in a decade.


| Asset | Units / Beds | Occupancy | AY 26-27 NOI | Value @ 5.50% | Debt | Vehicle Interest |
|---|---|---|---|---|---|---|
| The Mansion | 13 / 52 | 100% | $964K | $17.52M | $9.43M @ 3.75% | $1.21M |
| East Village Flats | 40 / 117 | 93% | $1,251K | $22.74M | $13.19M @ 5.97% | $0.72M |
| The Gaslamp | 19 / 60 | 93% | $726K | $13.19M | $9.43M @ 3.29% | $0.34M |
| Total | 72 / 229 | — | $2,940K | $53.46M | $32.04M · 4.53% wtd | $2.27M |
Values at the offering basis — a 5.50% cap rate on AY 26-27 budgeted NOI per the firm's 8/5/26 budget & cash forecast, at actual 8/1/26 debt balances. Vehicle interest equals 30% of Brickstone’s position in each partnership — 50% (1101), 25% (2885), 30% (910). Debt figures are current balances; all three loans are fixed-rate agency financings maturing Nov 2029 (1101), Jun 2030 (910) and Jun 2031 (2885).


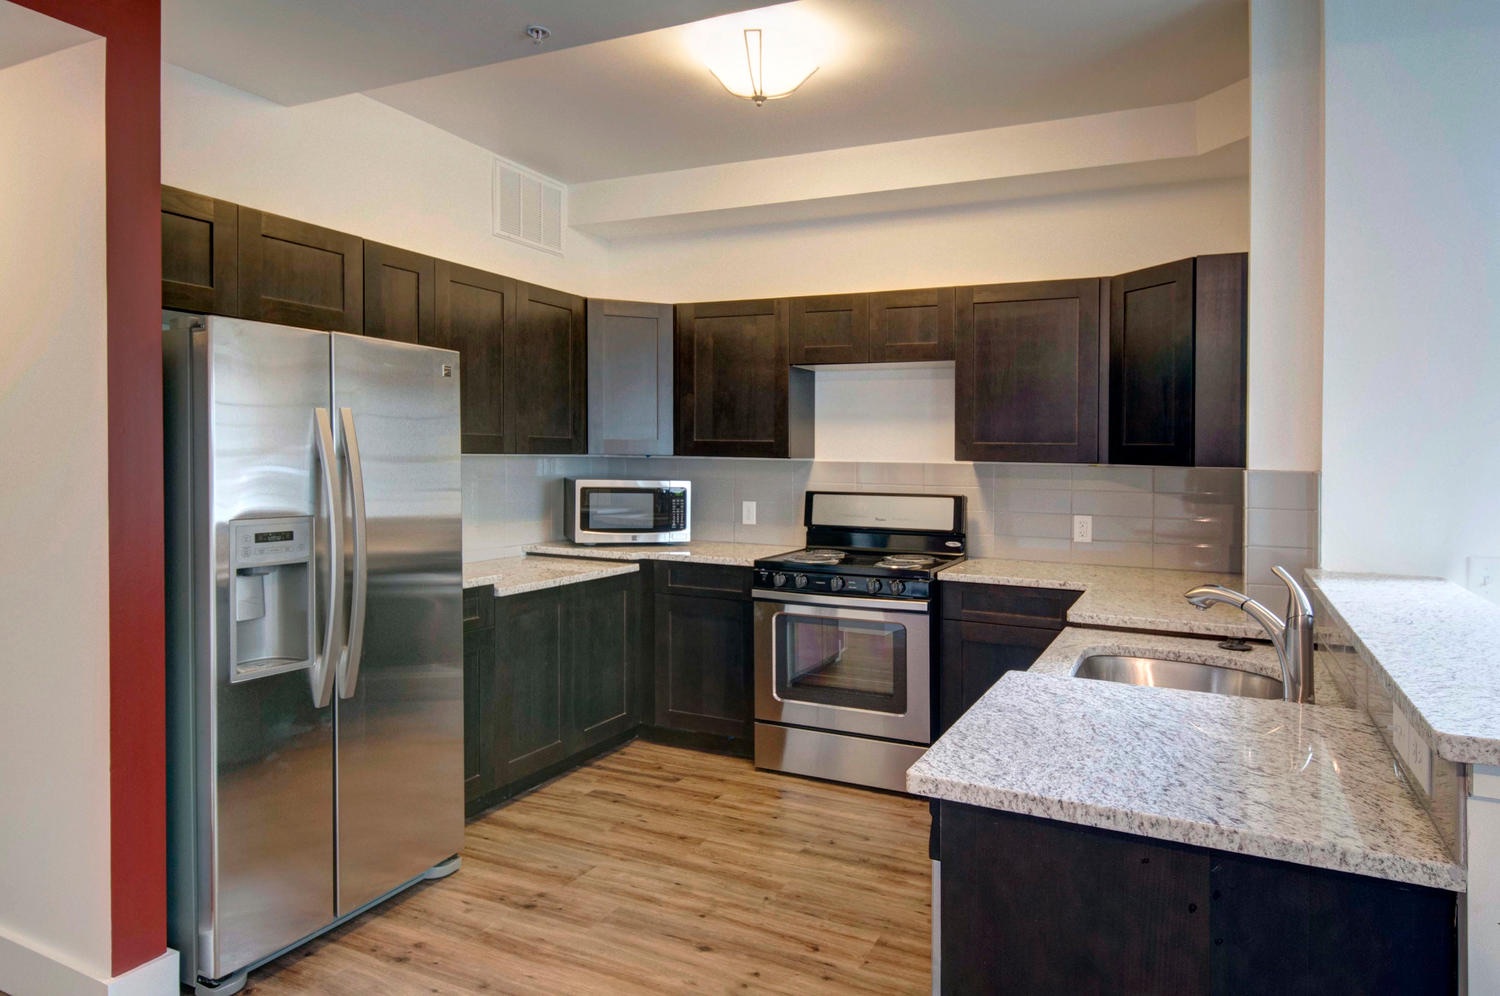
The Mansion · 1101 University Ave — directly across from campus · renovated interior, representative unit
A 1924 landmark on University Avenue, directly across the street from CU Boulder — repositioned by Brickstone in 2011 into 13 units and 52 beds of the most defensible student housing in the market. The Mansion is 100% occupied for 2025-26 and was 100% pre-leased for 2026-27 with zero concessions — the third consecutive cycle it has fully leased — at a signed rate of $2,021 per bed, while the broader Boulder market absorbed 10-11% vacancy.
The AY 26-27 budget produces $964K of NOI on a ~74% margin. Debt is a 3.75% fixed Freddie Mac note maturing November 2029 — 54% LTV at the offering basis. The 2027 budget plans $67,000 of distributions to Brickstone from the asset.
| Units / beds | 13 / 52 |
| Occupancy · pre-lease | 100% · 100% |
| Signed rate (AY 26-27) | $2,021 / bed |
| AY 26-27 NOI (budget) | $963,855 |
| Value @ 5.50% cap | $17.52M · $337K/bed |
| Debt (3.75% fixed · Nov 2029) | $9.43M |
| Partnership equity NAV | $8.10M |
| Brickstone interest · conveyed 30% | 50% · $1.21M |
| 30% of Brickstone fees — founder shares (2027) | $14.0K / yr |


East Village Flats · 2885 E Aurora Ave — developed by Brickstone, delivered 2014 · representative interior
A 40-unit, 117-bed community developed ground-up by Brickstone and delivered in 2014, in the East Aurora corridor alongside The Lodge. East Village Flats is 88% pre-leased for 2026-27 with occupancy forecast at 93%, at a blended rent of $1,364 per bed — holding rate through the current supply wave. The AY 26-27 budget produces $1.25M of NOI, the largest earner of the three seed assets.
Debt is a fixed-rate Freddie Mac note maturing June 2031 — the longest runway in the seed pool — at a 58% LTV on the offering basis. Q1-2026 income ran 10.8% ahead of budget, and the 2027 budget plans $220,000 of distributions to Brickstone.
| Units / beds | 40 / 117 |
| AY 26-27 occupancy · pre-lease | 93% · 88.0% |
| Blended rent (AY 26-27) | $1,364 / bed |
| AY 26-27 NOI (budget) | $1,250,949 |
| Value @ 5.50% cap | $22.74M · $194K/bed |
| Debt (5.97% fixed · Jun 2031) | $13.19M |
| Partnership equity NAV | $9.56M |
| Brickstone interest · conveyed 30% | 25% · $0.72M |
| 30% of Brickstone fees — founder shares (2027) | $23.0K / yr |
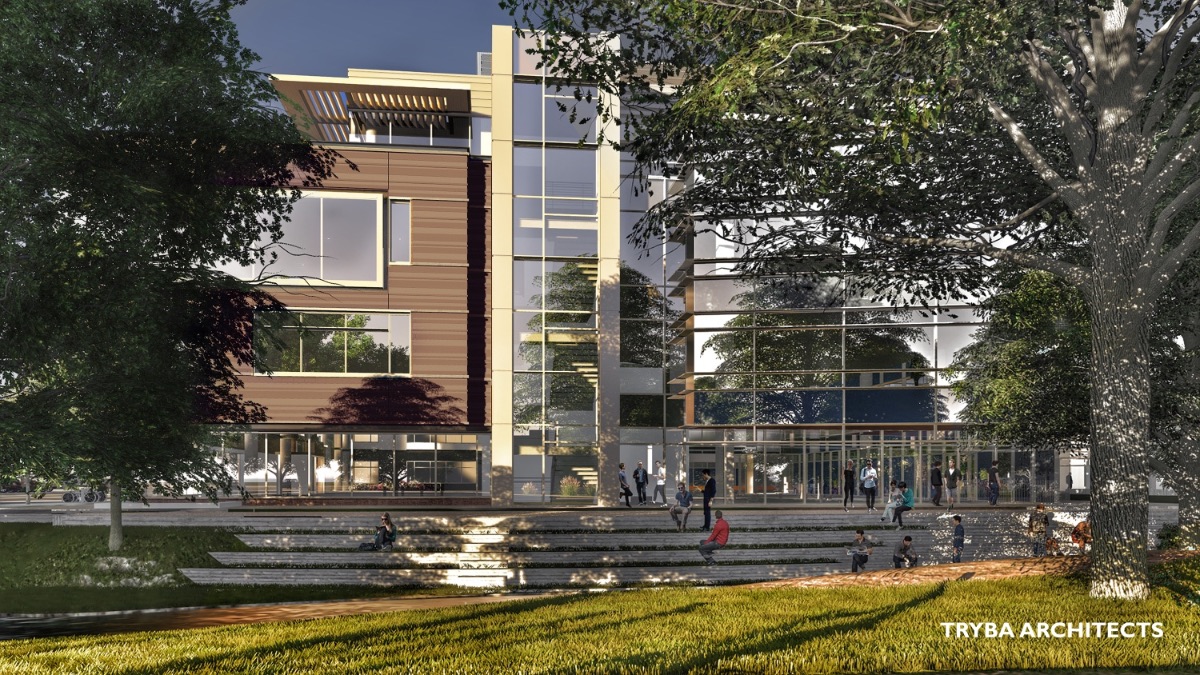
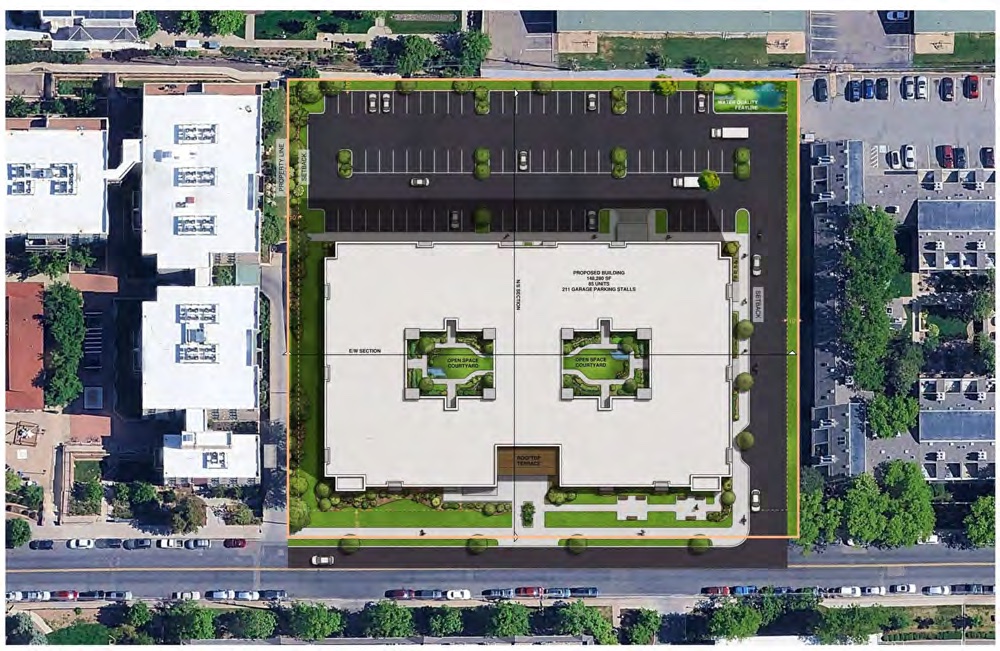
East Village Flats occupies one of the last large remaining development sites adjacent to the University of Colorado Boulder — approximately 2.2 acres on the East Aurora corridor — with entitlements for more than 400 new beds in process and expected to be complete next year. The site carries materially more entitled capacity than the 117 beds it holds today. Brickstone has designed a new purpose-built student community of 100 units and 400 beds in two buildings — a five-story building (Building A) and a four-story building (Building B) — with a primary two-level building of 66 units and a secondary two-level building of 34 units, joined by a 3,000 SF clubhouse and amenity building. Located one block from Boulder's East Aurora student-housing corridor, the site's below-grade parking and street-level retail plan bring institutional-grade product to a corridor Brickstone already owns on both sides.
| Units / beds | 100 / 400 |
| Buildings | Building A — 5 stories · Building B — 4 stories |
| Primary building | 66 units · two levels of parking below |
| Secondary building | 34 units · two levels of parking below |
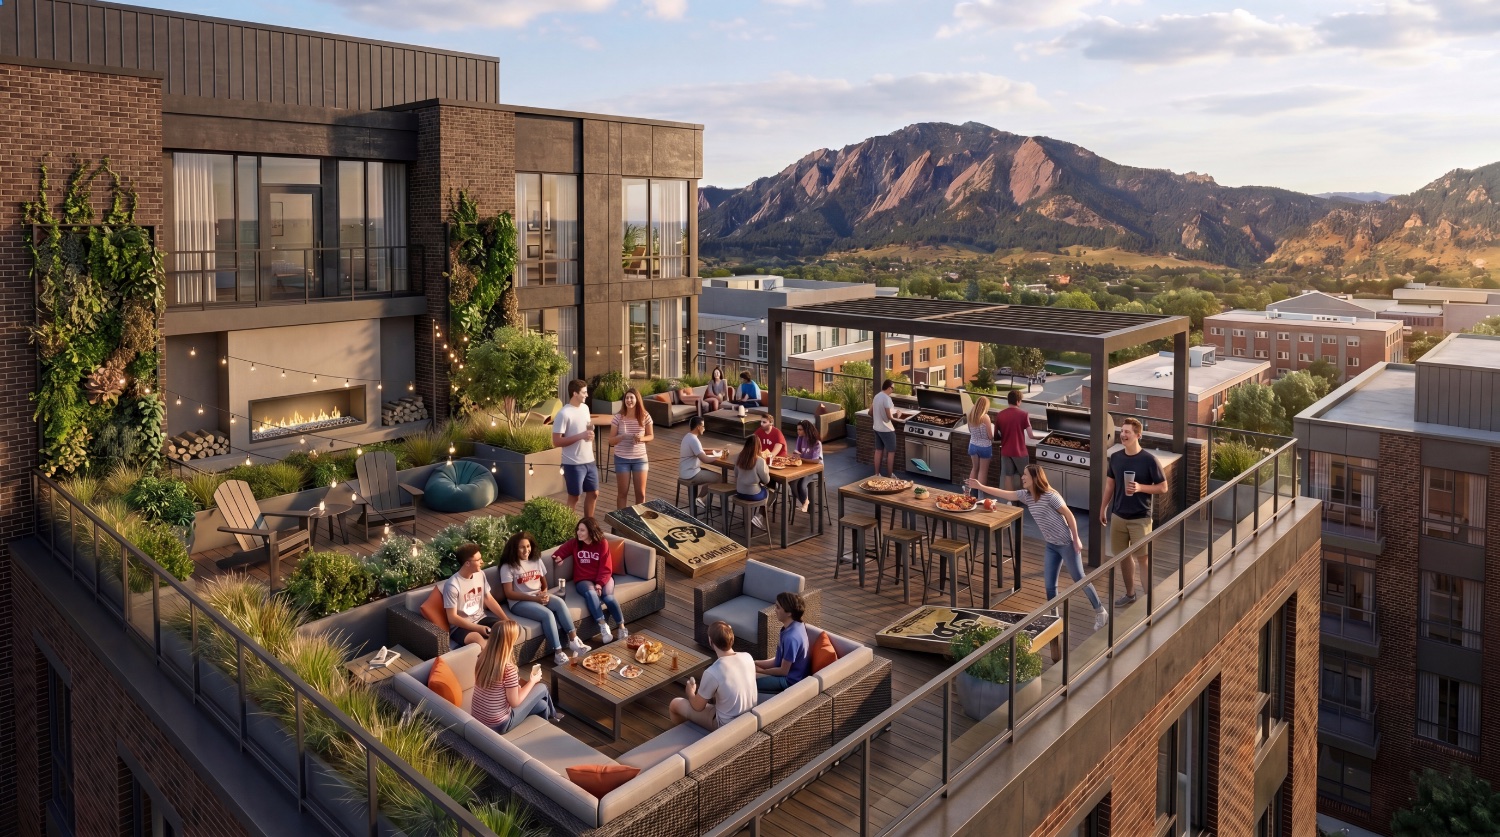
| Clubhouse & amenities | 3,000 SF — roof deck, fitness, study suites |
| Site | ~2.2 acres · one block from the East Aurora student corridor |
| Roof deck | Clubhouse roof deck with Flatirons views |
| Study | Collaborative tech room · group rooms · individual pods |
| Fitness | Full fitness center |
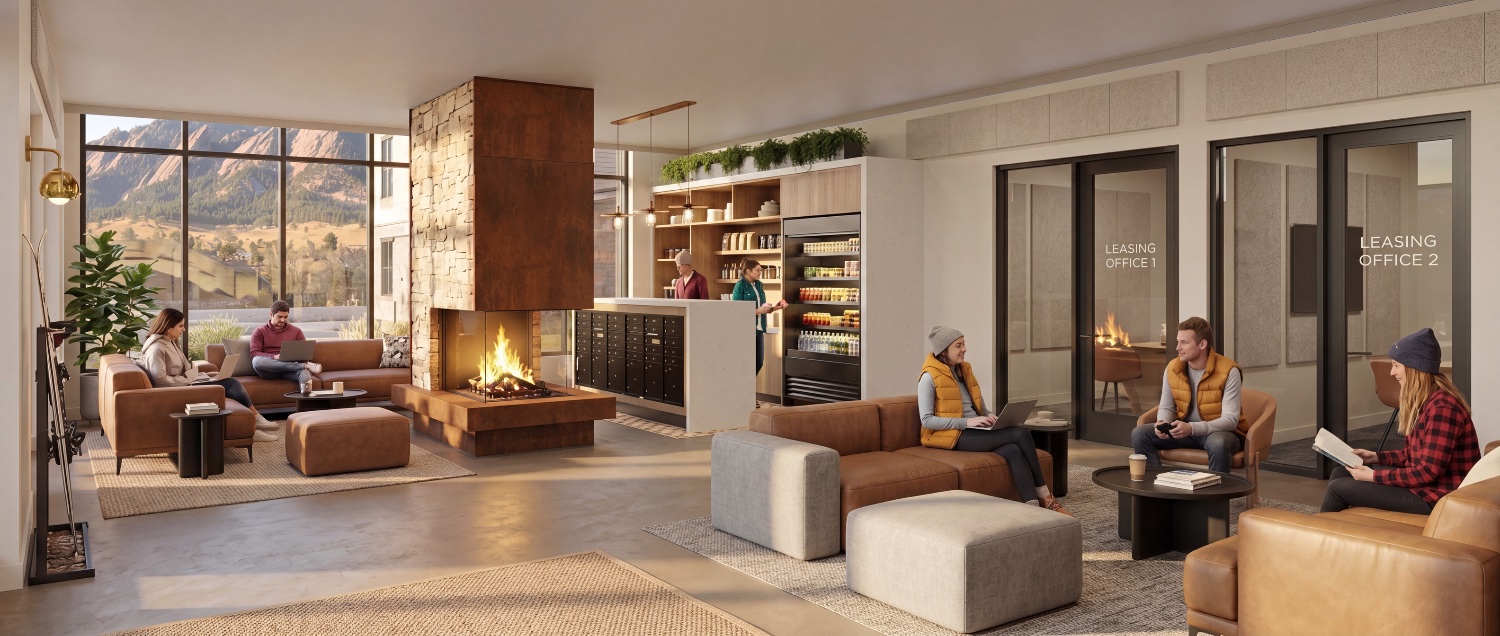
| Lobby | Hotel-grade lobby & lounge |
| Parking | Below-grade, two levels under each building |
| Entitlements | 400+ beds in process — completion expected 2027 |
Illustrative renderings of the proposed 2885 East Aurora community. Final design and scope are subject to City of Boulder review and may differ materially or may not be implemented.


A 19-unit, 60-bed community developed by Brickstone and delivered in 2012 on 28th Street, minutes from campus. The Gaslamp is 90% pre-leased for 2026-27 with occupancy forecast at 93%, at a blended rent of $1,627 per bed, and carries the lowest coupon in the Brickstone portfolio — 3.29% fixed — with the loan maturing June 1, 2030.
The AY 26-27 budget produces $726K of NOI at a roughly 64% margin. At the offering basis the asset carries a 71% LTV, and the 2027 budget plans $56,000 of distributions to Brickstone. Q1-2026 income ran 5.8% ahead of the prior year.
| Units / beds | 19 / 60 |
| AY 26-27 occupancy · pre-lease | 93% · 90.0% |
| Blended rent (AY 26-27) | $1,627 / bed |
| AY 26-27 NOI (budget) | $725,569 |
| Value @ 5.50% cap | $13.19M · $220K/bed |
| Debt (3.29% fixed · Jun 2030) | $9.43M |
| Partnership equity NAV | $3.77M |
| Brickstone interest · conveyed 30% | 30% · $0.34M |
| 30% of Brickstone fees — founder shares (2027) | $14.5K / yr |
The seed package is priced from a transparent, two-part build: partnership equity (value less debt, times Brickstone’s ownership held in the sidecar entity, times the fund’s 30% ownership of that entity) plus the fee strip (30% of Brickstone’s budgeted seed-asset fees — conveyed to the founder shares — valued on typical GP-stakes economics). The offering basis applies a 5.50% cap rate to each asset's AY 26-27 budgeted NOI at actual 8/1/26 debt balances. Move the cap rate and the fee multiple — every figure recomputes.
| NAV Build | AY 26-27 NOI | Value @ 5.50% | Less Debt | Equity NAV | Vehicle Interest |
|---|
| Brickstone fee income — 2027 corporate budget | $171,610 / yr |
| Conveyed to founder shares — 30% | $51,483 / yr |
| GP-stakes market range — 8x to 12x fee-related earnings | $412K – $618K |
| DCF cross-check — 3% growth · 8% discount · 8x terminal | $645K (12.5x) |
| Applied — 10x fee-related earnings (below DCF) | $514,830 |
| Brickstone 2027 distributions — Mansion / EVF / Gaslamp | $67,000 / $220,000 / $56,000 |
| Allocated to founder shares (30% of the sidecar entity) | $20,100 / $66,000 / $16,800 = $102,900 |
| PV of distributions (15 yrs, 3% growth, 8%) + PV of terminal NAV | $2.73M vs. $2.27M basis |
Deliberately conservative: debt is held at current balances (two of the three loans amortize monthly), promotes conveyed to the vehicle are valued at $0 in the seed, and NOI is the AY 26-27 budget at forecast occupancy — 93% at East Village Flats and The Gaslamp.
A five-year hold of the seed package, growing NOI and fees at 3.0% annually with debt held flat, marked at three exit bases — from no cap-rate recovery at all to a full recovery to 4.25%. New-deal deployments, promote income and refinancing proceeds are not modeled; they layer on top.
| Scenario — Year-5 Mark | Package Value (Yr 5) | Vehicle Gross IRR / MOIC | Net LP IRR / MOIC1 |
|---|
1. Net to investors after the 8% cumulative compounding preferred return and the 70/30 split, treating the full seed package as investor-funded. Assumes year-one cash of $154K growing 3.0% annually; year-5 package value = the conveyed equity share of (year-5 NOI ÷ exit cap, less current debt) plus the fee strip at 10x on year-5 fees. Before vehicle-level expenses and taxes. Illustrative only — see Disclosures.
With no cap-rate recovery and no new deals, the seed still produces a 1.49x / 9.1% net investor outcome — the 8% preference paid in full.
Every Brickstone deal the fund helps capitalize adds 30% of its GP economics to the vehicle. None of that — no promote, no new fee, no refinancing — is in these numbers.

Brickstone is planning new deal flow in the Southeastern United States in value-add multifamily — new opportunities developing as a result of the new yield regime and the oversupply of the last few years — alongside continued Boulder recapitalizations. Offering proceeds fund the GP side of that growth:
Brickstone commits real cash — frequently more than 10% of equity — to every deal it sponsors. The vehicle may fund up to 100% of the GP co-investment on any transaction — Brickstone determines the allocation between the fund and other co-investors deal by deal — and on those deals receives 30% of the fees and promotes. The program model assumes a 30% funding share.
Reset bases, distressed sellers and a closed construction pipeline are producing the entry conditions Brickstone waits for. The firm intends to bring its Boulder playbook — heavy sponsor cash, tax-advantaged structuring, patient holds — to selected Southeastern markets.
Talent and digital infrastructure — including senior digital leadership, direct-to-investor channels and data-driven asset management across the portfolio.
Capacity to warehouse deposits, fund pursuit costs and move at closing speed — the operational edge that wins off-market transactions.
A capitalized guaranteeing entity for lender liquidity and net-worth covenants, non-recourse carve-out (“bad-boy”) guarantees, and other governance-related carve-outs — capacity that lets Brickstone close institutional financings across a larger program.

To size what new deal flow means for the vehicle, Brickstone modeled its standard transaction: a $100M project at 35% equity / 65% debt, a five-year hold, a 2.0x gross equity multiple (~16% deal-level IRR), an 8% compounding investor preference with a 20% promote above it, a 1% acquisition fee (on a $95M purchase), a 1% exit fee (on the $126M sale), a 30 bps asset-management fee on total asset value, and a 10% GP co-investment ($3.5M, pari passu). Five GP streams result — the vehicle owns 30% of each and funds 30% of the co-invest:
| GP Stream | Basis | Timing | GP Receives | Vehicle (30%) |
|---|
Per $100M capitalized, the vehicle deploys $1.05M of co-invest and receives $4.36M back — $1.18M of fees, $1.08M of promote and $2.10M of co-invest return — 4.2x the dollars deployed. A deal LP still nets 14.5% / 1.89x after the promote at these terms.
Applying those unit economics to Brickstone capitalizing $1.0 billion (Scenario A), $2.0 billion (Scenario B) or $3.0 billion (Scenario C) of new projects evenly over ten years — $100M / $200M / $300M per vintage, each vintage exiting at 2.0x in year five. Fund-level figures include the $2.8M seed package and its cash flow; refinancings, seed revaluation and above-standard exits are excluded. Select a program size — every figure recomputes.
| Vehicle Receipts Build ($M) | Acq Fees | AMF | Exit Fees | Promote | Co-Invest Return | Seed Cash + Terminal | Total |
|---|
| Capitalized Value of the Fund’s New-Deal Fee & Promote Stream | Run-Rate Fees (yrs 6–10) | Run-Rate Promote (yrs 6–10) | 3.0x Multiple | DCF @ 15% |
|---|
1. Vehicle capital = seed package ($2.8M) plus cumulative co-invest draws ($10.5M / $21.0M / $31.5M). Peak net capital outstanding is only $4.3M / $6.6M / $9.0M — from year 6, harvested distributions fund new vintages, leaving ample capacity inside the $30M initial envelope — the $20M follow-on remains in reserve. 2. Net to investors after the 8% cumulative compounding preferred return — which accrues only on called capital (seed at closing; co-invest called annually as deployed) — and the 70/30 split. The capitalized value of the fee & promote stream is informational and is not added to any return figure. Illustrative only — deal count, pacing, leverage and outcomes will vary; see Disclosures.
Once the first vintages exit, promote and co-invest returns recycle into new deals — the program runs on roughly $4–9M of net capital at its peak.
These scenarios assume standard execution. The Lodge returned 3.8x on its initial partnership; Parker off Pearl 4.4x over eleven years.
| Offering size | Up to $30,000,000 · $250,000 minimum (manager may make exceptions) |
| Follow-on round | Up to $20,000,000, exercisable anytime during fund life |
| Founder shares | First $10,000,000 — receive the seed package |
| Preferred return | 8% cumulative, compounding, on called capital only |
| Split above preference | 70% Brickstone / 30% investors |
| Fund share of GP economics | 30% — only on deals the fund helps capitalize |
| Capital calls | Seed at closing; co-invest called annually as deployed |
| 30% of the Brickstone sidecar entity (holding 50% / 25% / 30%) @ 5.50% cap | $2,270,425 |
| 30% of Brickstone’s seed-asset fees ($51,483/yr) at 10x | $514,830 |
| Total seed package · consideration to Brickstone | $2,785,255 · ~$2.3M |
| Year-1 cash · yield | $154,383 · 5.5% |
| Allocated 2027 distributions to founder shares | $102,900 / yr |
| Acquisition fee | 1.00% of purchase price |
| Exit fee | 1.00% of gross sale price |
| Asset-management fee | 30 bps on total asset value, annually |
| Promote | 20% of LP profits above an 8% compounding preference |
| GP co-investment | 10% of equity, pari passu — fund may provide up to 100%, allocated by Brickstone per deal (30% modeled) |
| Underwriting standard | 2.0x gross equity multiple · 5-year hold · 35% equity |
| GP economics per $100M · fund share | $11.04M · $3.31M profit on $1.05M deployed |
| Program | Fund Capital | Fund Receipts | Net LP IRR / MOIC | Peak Capital |
|---|
Seed valuation: AY 26-27 budgeted NOI at actual 8/1/26 debt balances (8/5/26 Budget & Cash Forecast). Fee stream valued at 10x fee-related earnings — inside the 8–12x GP-stakes market range and cross-checked by DCF (3% growth, 8% discount, 8x terminal ≈ 12.5x — the applied 10x is below it). Program figures over a 15-year horizon with even deployment across ten vintages; net to investors after the 8% preference on called capital and the 70/30 split. Capitalized value of the fund’s new-deal fee and promote stream is shown two ways — a 3.0x multiple on the steady-state (years 6–10) annual run-rate, and a 15% DCF of the full 15-year stream — which converge; this value is informational and is not added to any return figure. Illustrative only — see Disclosures.
Opens an email to Daniel H. Otis — or call directly at 303.815.6705. Detailed historical performance and the data room are available on request.

| Education | North Dakota State, 2005 |
| Executive | Harvard Real Estate, 2010 & 2013 |
| Service | U.S. Air Force veteran |
| Boards | Folds of Honor · AOPA (past) |
| Athletics | Division I pole vaulter |
| Pursuits | Aviator · Piano, 30+ yrs |
Daniel H. Otis is the Founder and Principal of Brickstone Partners. Founded as a commercial real estate private-equity firm in 2001, the firm has directly completed more than $1 billion of multifamily, student housing, retail and office investment and development deals. Dan started the company at age 20 while in college, redeveloping and investing in student housing around his alma mater.
His investment thesis has been carefully crafted and consistently executed: pursuing opportunities with an asymmetry of risk and reward — generating opportunistic yield with less risk than normal. He has brought that thesis to life repeatedly, in some of the best locations and markets in the country, generating opportunistic yields to investors and attracting capital from some of the largest family offices and institutions in the world.
First and foremost an accomplished family man and father of four young children, Dan has been married to his wife for more than 15 years. He is a veteran of the United States Air Force, a former Division I pole vaulter and an accomplished aviator — flying both fixed-wing aircraft and helicopters — who enjoys an active life — hunting, riding dirt bikes in the mountains, and flying with his kids — and has played piano for more than 30 years. He is a past board member of Folds of Honor and the Aircraft Owners and Pilots Association (AOPA).
Brickstone has owned and operated The Lodge since 2015, through two full-cycle recapitalizations (2019 and 2022) — both returning strong profits to investors while Brickstone retained ownership — and more than $17 million of reinvestment; the asset is exceptionally well known to the principal.

| Education | MBA & BBA, Mercer University |
| Credential | Licensed CPA (Tennessee) |
| Experience | 20+ yrs senior finance |
| Prior | Highland Ventures · HealthTrust · Landmark |
| Based | Nashville, Tennessee |
Jon W. Hill, CPA brings more than 20 years of senior finance and accounting leadership across complex real estate platforms, private equity, and multi-entity capital structures. As CFO of Brickstone Partners, he oversees all financial operations — treasury, debt compliance, investor reporting, tax strategy, and capital planning across the firm's student housing and multifamily portfolio.
Prior to Brickstone, Jon served as CFO of Highland Ventures, a Nashville-based family office with holdings spanning real estate, healthcare, retail and foodservice, where he executed more than 33 acquisitions and financings totaling over $150 million across 16 states, directing strategic financial planning, banking relationships, and buy- and sell-side M&A.
Earlier, Jon held senior finance roles at HealthTrust — where he helped coordinate the sale of a major subsidiary to Blackstone — and at Landmark Properties, one of the nation's largest student-housing operators, overseeing accounting, fund management and investor reporting across a portfolio exceeding $7 billion in assets. At Landmark he managed financial operations for multiple private-equity real estate funds, served as primary finance contact for major institutional equity partners including sovereign wealth funds, and built the reporting infrastructure for a new fund capitalized at more than $1.5 billion.

| Education | M.Arch, CU Boulder — first in class |
| Credential | Licensed architect |
| Experience | 25+ yrs design & development |
| Delivered | 1.5M+ SF · 500+ residences |
| Affiliations | ULI · AIA · NCARB |
Jeff J. Dawson is founder and managing principal of STUDIO Development Services, a real estate development consulting firm specializing in owner's representation, project management, needs assessment and facilities planning. The SDS team supports Brickstone Partners with owner's representation and project management, drawing on decades of design, planning and construction experience. Jeff is also a licensed architect and founder of STUDIO Architecture, a full-service Boulder design firm focused on commercial office, retail and mixed-use multifamily — student housing, luxury and senior housing across Colorado, Minnesota, Missouri and Wisconsin.
Jeff has personally been involved in the development of over 1,500,000 SF of construction, 500+ multifamily residences and 500,000 SF of office, retail and institutional space over the past 25 years. He has worked with Brickstone for over five years, helping deliver more than 300 apartment units to the Boulder student-housing market.
In 2007 Jeff left a principal role at one of Colorado's largest architecture firms to become a partner in development company Morgan Creek Ventures, completing luxury condo, office and apartment projects across Boulder County. He was first in his class earning his master's in architecture at the University of Colorado, and is active in the Boulder community — City of Boulder Design Advisory Board, Urban Land Institute, AIA and NCARB. He and his wife Elizabeth have two sons in college; he grew up surfing in Southern California and now skis and hikes in the Colorado mountains.

| Education | MBA, University of Virginia |
| Undergraduate | BBA, TCU — magna cum laude |
| Experience | 15+ yrs family office |
| Boards | Stonebridge · Low Tide · SOLVE FSHD · Brickstone |
| Affiliations | YPO · Family Office Principals |
Jason Gaede serves as Chairman of the Brickstone Board of Advisors. He is currently President of House of Wilson, where he manages the family office for the Wilson family — founders of lululemon — overseeing the family's investments, tax, legal, accounting, family governance, communications, and the Wilson 5 Foundation.
He currently participates on the boards of Stonebridge Companies, Inc., Low Tide Properties, Inc., SOLVE FSHD, and Brickstone Properties. With over 15 years of experience in the family-office sector, Jason previously held the position of President and Chief Investment Officer at Copford Capital Management, LLC, a prominent single-family office based in Denver.
He is a member of Young Presidents' Organization (YPO) and an active participant in the YPO Family Office Principals Group. Prior to earning his MBA from the University of Virginia, he accumulated five years of experience in investment banking and private equity. Jason is a magna cum laude graduate of Texas Christian University, holding a BBA in Finance and Accounting.

| Education | University of St. Thomas |
| Experience | Founder, Castalian Partners (2016) — $200M+ managed |
| Prior | Decade as research analyst, Punch & Associates |
| Boards | Willmar Stingers (Chairman) · Bespoken Spirits |
| Residence | Orono, Minnesota |
James Gibson is the CEO of The Castalian Company, a private holding company focused on owning and building exceptional businesses while making strategic investments across the public and private markets.
Prior to The Castalian Company, James founded Castalian Partners in 2016. The firm grew to manage more than $200 million for high-net-worth individuals and leading institutional investors. Over nearly a decade of operations, Castalian earned a reputation for rigorous fundamental research and delivered strong absolute returns across multiple market cycles. Before launching Castalian Partners, James spent a decade as a research analyst at Punch & Associates Investment Management.
In addition to his role at The Castalian Company, James serves as Chairman of the Willmar Stingers, a member club of the Northwoods League, and as a Director of Bespoken Spirits, a private technology company transforming the spirits industry. James is a graduate of the University of St. Thomas and resides in Orono, Minnesota, with his wife and five children.
Daniel H. Otis, Principal · 303.815.6705 · danotis@brickstonepartners.com
Strictly Confidential · September 2026 · Franklin, Tennessee. This website is furnished on a confidential basis for discussion purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any security. See Disclosures above.